CreditWise from Capital One

Screenshots
Details
- Rating
- 40.63K reviews
- Version
- 1.150.0
- Developer
- Capital One Services, LLC
Analysis by Norviv
I usually think of credit-monitoring apps as tools for one person, one account, and one phone. CreditWise from Capital One works best with that expectation, but it can still be useful in a household where people talk about money together. I tested it as a finance app rather than treating it like a full banking replacement, and that distinction matters: its main appeal is giving an individual a simple place to check a credit score and watch for changes without paying for access.
The app is free, carries an Everyone age rating, and comes from Capital One Services, LLC. It has built a strong audience on mobile, with a 4.6 average from roughly 116 thousand ratings and more than 5 million installs. Those figures do not automatically make an app right for every family, but they do suggest that CreditWise has become a familiar option for people who want basic credit awareness on a phone.
How CreditWise fits into a shared household
A realistic example is a couple preparing to rent a new home. One person may be handling the application while the other keeps track of bills, subscriptions, and upcoming expenses. CreditWise can give the account holder a quick way to check their own credit position and notice changes, while the pair discusses broader household decisions separately. I like this division because it avoids pretending that a shared financial goal means every financial account should be shared.
The app is not a household dashboard. I would not install it on a family tablet and expect several people to use one profile comfortably. Credit information is personal, and the useful boundary is simple: the person whose credit is being monitored should control the account and decide what to discuss with others. A partner can help interpret a notification or remember a payment date, but that does not turn the app into a joint credit file.
This matters especially when a device stays in a common room. A phone or tablet may be shared casually, yet a credit score and monitoring alerts are still sensitive. I would use the app on my own secured device whenever possible, rather than leaving an active session available to children, guests, or other household members. That is not a special CreditWise family feature; it is a sensible privacy habit for any personal finance service.
For coordination, the most practical workflow is to check the app individually and then discuss only the information needed for the household decision. For example, if we were comparing rental options, I might confirm that I have reviewed my credit status without passing around my login or leaving the screen open. If both adults need to understand their own credit positions, each should use an account intended for them instead of treating one profile as a shared record.
The strongest household use is coordinated awareness, not shared access. That distinction prevents an easy mistake: assuming that because two people manage rent or loan payments together, they should also use one credit-monitoring identity. CreditWise is more useful when it supports responsible conversations while keeping personal account boundaries intact.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Starting with the right expectations
CreditWise is a focused credit-monitoring tool, not a complete replacement for a bank app, card issuer app, budgeting package, or identity-management service. When I open it, I approach it with one question: has anything about my credit situation changed that deserves attention? That narrow purpose makes it approachable, but it also means I would not choose it as the only app for managing a household budget.
The free price is a meaningful advantage for someone who wants to begin monitoring without adding another monthly bill. It also makes the app easier to recommend to a younger adult who is learning how credit works or to a household member who has never checked their credit regularly. Still, “free” should not be confused with “complete.” A no-cost monitoring app can be valuable while leaving other financial tasks to separate services.
Before relying on it, I would make sure I understand whose information is connected to the account and which phone is being used. This is particularly important after changing phones, sharing devices, or helping a relative set up the app. I would not enter another person’s credentials simply because they are a partner or family member. Helping someone navigate a screen is different from taking control of their financial identity.
The current version is 1.150.0, and the app requires at least iOS 11. That makes it accessible on a broad range of compatible Apple devices, although I would still keep the operating system and the app updated where possible. Finance apps deserve extra care around updates because reliability, security fixes, and login behavior can matter more than cosmetic changes.
One useful setup habit is to decide in advance what an alert means in your household. A notification should prompt the account holder to open the app, review the detail, and compare it with recent financial activity. It should not automatically become a reason to accuse a partner, cancel a card, or panic about identity theft. Treating an alert as a starting point for verification is calmer and more reliable than reacting to the first message.
What coordination looks like in everyday use
CreditWise can fit into a weekly or monthly money routine, but I would keep the routine short. I might check it while reviewing bills, then note whether anything needs follow-up. If a household is preparing for a major application, such as a rental or credit product, the person applying can review their own information and communicate the relevant outcome without exposing every detail of the account.
This approach is helpful when one person is more comfortable with technology than the other. The technically confident person can explain where to look and what a notification means, while the account owner remains the person who signs in and makes decisions. That arrangement reduces the chance that a helpful relative accidentally becomes the unofficial keeper of someone else’s financial access.
There is also a trade-off when a household has two adults with separate credit histories. CreditWise may be useful for one person, but checking one profile does not tell you everything about the other person’s position. If both people are applying together, each should consider their own credit-monitoring arrangement. I would never infer that one person’s result represents the household as a whole.
Another practical point is timing. A credit-monitoring app is most useful when it becomes part of a consistent habit, not when it is opened only after a suspicious message or a rejected application. Checking occasionally can help a user recognize normal patterns and distinguish a familiar change from something that deserves investigation. It is not a substitute for reading statements, confirming payments, or contacting a provider directly when a transaction looks wrong.
I also prefer discussing trends rather than turning the score into a household competition. Credit histories can differ for many personal reasons, and a number on a screen is not a complete measure of financial responsibility. In a shared home, the app works better as a prompt to plan and verify than as a scoreboard between partners or relatives.
Age, trust, and personal boundaries
The Everyone rating makes CreditWise approachable from an age-classification perspective, but I would still distinguish between being allowed to use an app and being ready to manage credit information. A teenager may be curious about credit, while an adult may be responsible for the account. The right arrangement depends on trust, understanding, and the device being used, not just the label attached to the app.
For a young person learning about money, I would use the app as part of a conversation about privacy, passwords, suspicious activity, and the difference between checking information and changing financial accounts. I would not hand over an adult’s unlocked phone and assume that curiosity is harmless. A supervised explanation is better than unrestricted access to another person’s profile.
For an older relative, the challenge may be different. A family member might need help reading a notification or finding a particular screen. I would sit beside them, let them sign in themselves, and avoid storing their credentials on my device. This preserves dignity and makes it clearer who is responsible for the account.
Trust also matters between partners. Shared finances do not remove the need for consent. If one person wants to show their credit information, that should be a deliberate choice. If they do not, the other person should respect that boundary. CreditWise can support a conversation, but it cannot solve disagreements about financial transparency, and I would not use it as a tool for secretly checking up on someone.
That is one of the app’s limitations in a household context: its value depends heavily on good account habits outside the interface. No simple monitoring screen can replace an agreement about who manages bills, who receives alerts, and how unusual activity will be handled. I see CreditWise as a personal instrument that can sit inside a household plan, not as the plan itself.
Where it beats familiar alternatives—and where it does not
Compared with checking a credit score only through a bank or card issuer, CreditWise has the advantage of being centered on credit awareness rather than being buried among payments, transfers, and card controls. That focus can make it easier for someone who wants a dedicated place to look. The free access is another reason I would consider it before paying for a broader subscription.
Compared with a full budgeting app, however, CreditWise is much narrower. A budgeting service may be better for tracking spending categories, planning shared bills, or viewing household cash flow. If my main problem were overspending on groceries or coordinating utility payments, I would choose a budgeting workflow instead of expecting a credit-monitoring app to solve it.
Compared with a credit bureau’s own tools, the choice may come down to convenience and the kind of monitoring experience a person prefers. I would still treat any app as one part of a verification process and consult the appropriate official source when a major application or dispute requires precise documentation. CreditWise is convenient for awareness; it should not be the only place I turn when a formal correction or lender decision is at stake.
It is also not the best fit for someone who wants every financial account in one screen. A household that already relies on a bank’s integrated dashboard may prefer fewer apps and fewer logins. In that case, CreditWise’s dedicated focus may feel redundant. I would install it when its monitoring purpose adds clarity, not simply because another finance app is available.
Small habits that make the app more useful
My first tip is to separate “notice” from “confirm.” When CreditWise shows a change, I would review recent statements, emails, and account activity before deciding what happened. This prevents a household from mistaking a normal update for fraud or overlooking the need to contact a provider. The app can draw attention to a change, but the user still has to establish whether it is expected.
My second tip is to keep a private record of the date and reason for important checks, especially before a move, vehicle purchase, or other major application. I would not copy sensitive information into a shared note. Instead, I would record a simple reminder such as “reviewed credit monitoring” and keep the detailed account information inside the appropriate secure service.
My third tip is to decide who handles follow-up before an alert arrives. In a couple, that might mean the account owner checks the detail while the other person gathers household paperwork. In a multigenerational home, it might mean a trusted relative helps with phone support without signing in for the account holder. Clear roles reduce rushed decisions and make assistance less intrusive.
My fourth tip is to avoid checking obsessively. Frequent refreshing can turn a useful monitoring habit into anxiety, especially when a household is already under financial pressure. A regular, calm review is more productive than treating every small change as an emergency. If a serious concern appears, I would move beyond the app and contact the relevant financial institution or official credit resource.
Finally, I would be careful when changing devices. Before giving an old phone to another family member, I would sign out of finance apps and remove personal access according to the device’s normal security process. This is basic digital hygiene, but it is especially important when a shared household makes device hand-me-downs common.
My household verdict
I would recommend CreditWise to an individual who wants a free, focused way to stay aware of credit changes and who is comfortable keeping the account personal. It is particularly suitable for someone beginning to build a regular financial-checking habit, or for a household that wants one adult to monitor their own credit while discussing broader plans together.
I would skip it if the main need is joint budgeting, shared spending control, or a complete view of several people’s finances. I would also avoid treating it as a replacement for statements, lender communication, or formal credit-report follow-up. Its narrow purpose is a strength when you want that purpose, but a weakness when you expect an all-in-one family finance center.
The app’s long availability since Apr 12, 2016, its free price, and its broad audience make it an easy starting point. Still, the most important decision is not whether everyone in the home can open it. It is whether the right person uses it consistently and keeps the account boundary clear. My final view is positive: CreditWise from Capital One is a practical personal monitor that can support household coordination, as long as privacy, consent, and follow-up remain more important than convenience.
Frequently Asked Questions
01What is CreditWise from Capital One, and what does it do?
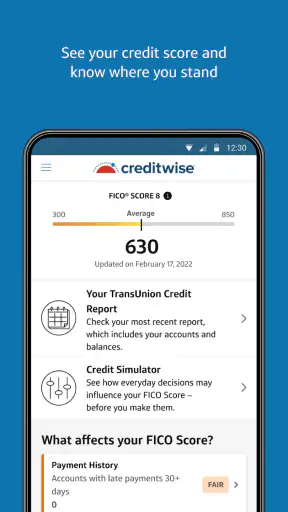
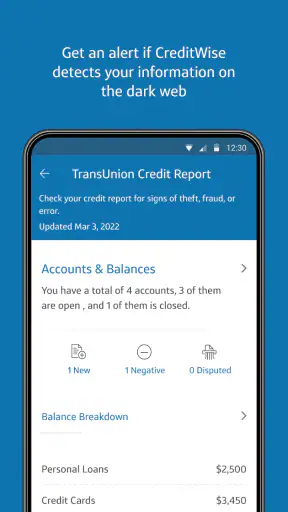
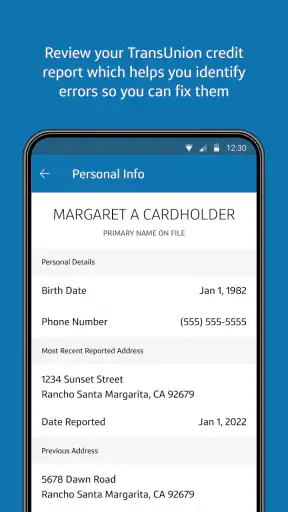
CreditWise is a free credit-monitoring app from Capital One that helps users understand and follow changes in their credit profile. It typically provides access to a VantageScore 3.0 credit score based on TransUnion data, credit report information, monitoring alerts, and educational tools. It is designed for tracking and learning, not for making final lending decisions.
02Do I need to be a Capital One customer to use CreditWise?
No. CreditWise is generally available to eligible users even if they do not have a Capital One credit card or bank account. You create or use a Capital One account to sign in, then complete the required identity verification. Availability and registration requirements can vary by location, so prospective users should check the current terms and eligibility details before downloading.
03Will checking my score in CreditWise hurt my credit?
No. Viewing your score or credit information through CreditWise is considered a soft inquiry and should not lower your credit score. The app is intended for personal monitoring, so checking it regularly can help you notice changes or possible errors without creating the impact associated with applying for a loan or credit card. Other companies may perform separate hard inquiries.
04How accurate is the credit score and information shown in CreditWise?
CreditWise commonly displays a VantageScore 3.0 calculated from TransUnion information, which may differ from the FICO score or scoring model used by a lender. Updates may not occur instantly, because they depend on when TransUnion and participating creditors report information. The app is useful for monitoring trends, but users should review official reports and lender requirements when accuracy is critical.
05What privacy and security features should I know about before using CreditWise?
CreditWise requires personal and financial information to verify your identity and provide monitoring services, so users should review Capital One’s privacy policy and permissions before signing up. The service may send alerts about report changes, but it cannot prevent identity theft on its own. Use a strong, unique password, enable available security protections, and report suspicious activity promptly.


